Bitcoin Traders Stack $4.5 Billion in Calls as $95K Bets Take Shape
Key Takeaways
- Deribit’s Oct. 30 $95,000 bitcoin calls hold 25,030.6 BTC in open interest.
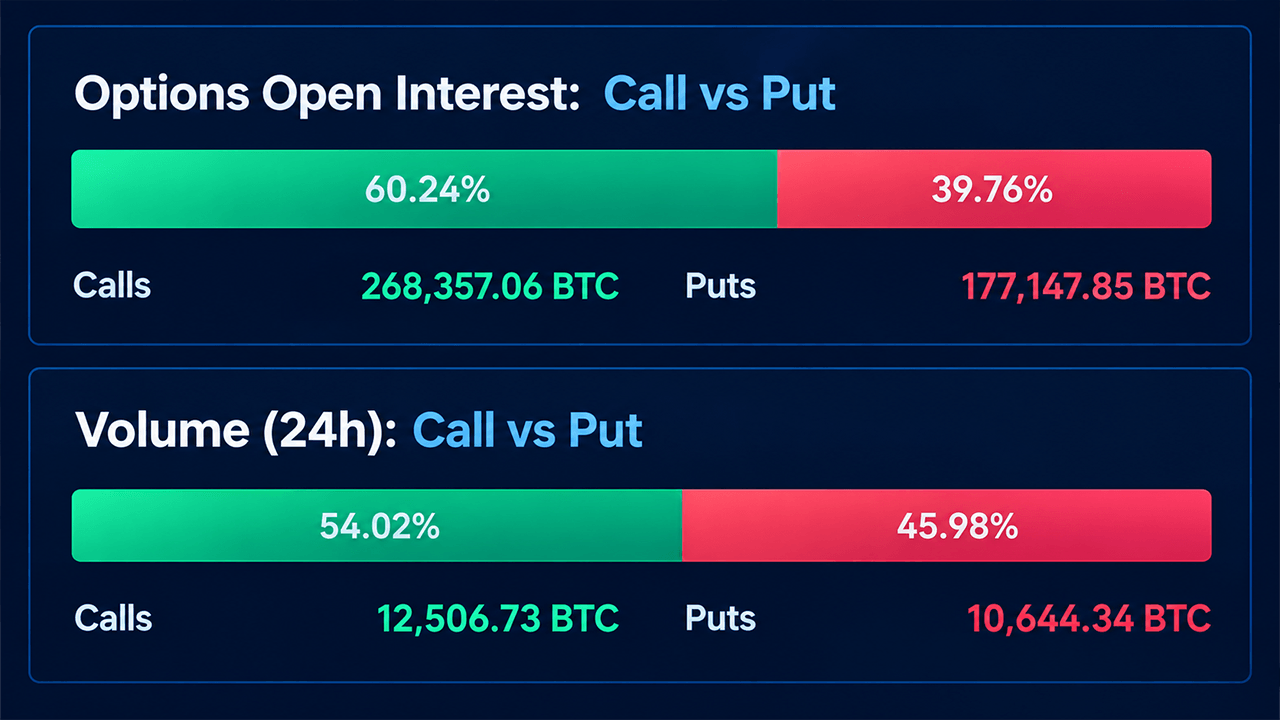
- Coinglass shows calls control 60.24% of bitcoin options interest, against 39.76% in puts.
- Bitcoin futures open interest stands at $51.7 billion, down 1.59% over 24 hours.
Bitcoin Traders Stack Billions in Bullish Calls as October Expiration Nears
Bitcoin traders have their sights on $95,000, but the options market has a rather different number in mind. As of Oct. 10, 2026, the derivatives giant Deribit‘s largest listed bitcoin options position contains 25,030.6 BTC in $95,000 calls expiring Oct. 30, representing roughly $2.07 billion in notional exposure at current prices.
Yet the same expiration carries a max pain estimate near $78,000, setting up an intriguing tug-of-war between bullish positioning and the price at which options holders collectively face the greatest theoretical losses.
Calls Dominate as October Expiration Approaches
Data from Coinglass shows call options account for 268,357.06 BTC, or 60.24% of total outstanding bitcoin options interest, compared with 177,147.85 BTC in puts. The 24-hour trading breakdown is closer, with calls representing 54.02% of volume against 45.98% for puts.
Although the figures favor calls, the difference between outstanding positions and daily trading activity suggests that bullish exposure is more pronounced in existing contracts than in the latest turnover. The concentration is especially striking at Deribit, where several enormous positions are clustered around higher strike prices.
Beyond the $95,000 contract, another 15,158 BTC sits in $90,000 calls, while $100,000 calls account for 14,561.8 BTC. Together, those three contracts represent approximately 54,750 BTC in open interest, equivalent to roughly $4.53 billion at a bitcoin price of $82,800. That’s a tidy sum tied to higher strikes, although open interest alone cannot establish whether participants are outright bullish, writing calls or hedging existing positions.
Max Pain Calculations Tell Another Story
The exchange-by-exchange picture complicates the bullish narrative considerably. For Oct. 30, Deribit’s estimated max pain stands near $78,000, while Binance and OKX hover around $81,000 to $82,000. Those calculations sit below bitcoin’s current market price, suggesting that the theoretical settlement points are considerably less ambitious than the strike prices attracting the largest outstanding call positions.
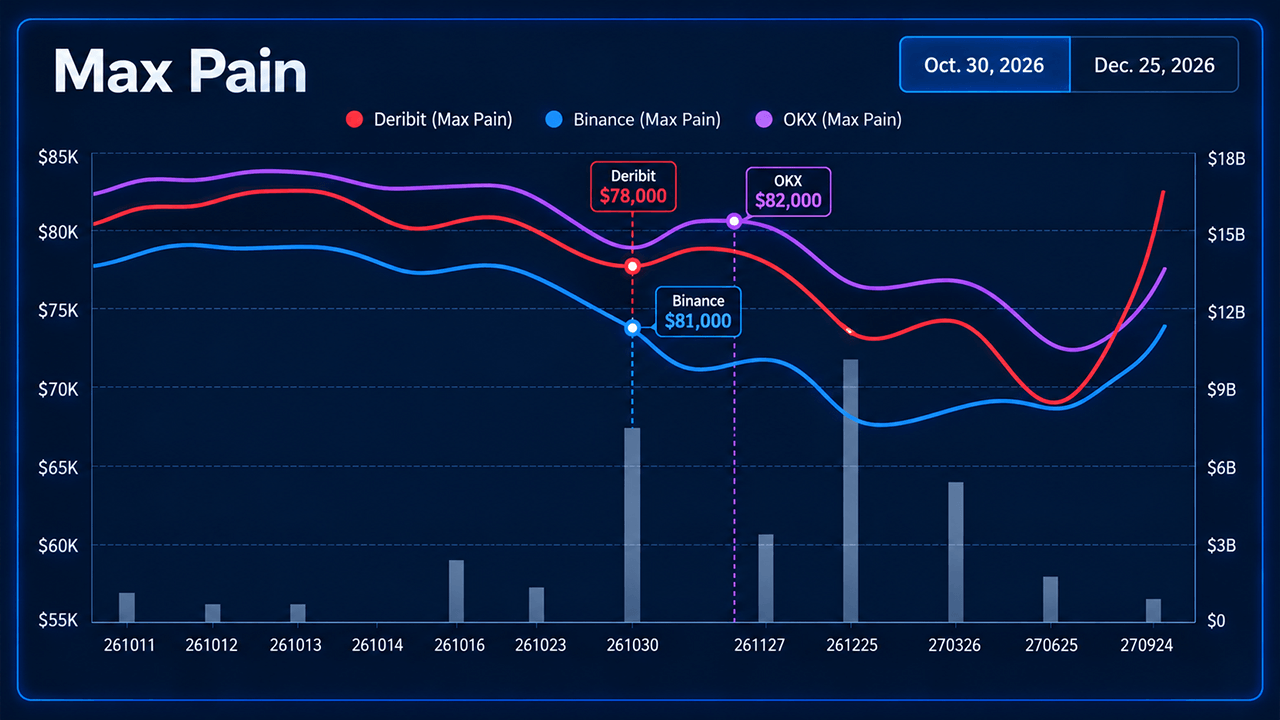
Looking further ahead, the discrepancies become even more pronounced. For the Dec. 25 expiration, Deribit’s max pain sits near $75,000, while crypto’s largest exchange by trade volume, Binance‘s estimate drops toward $62,500, and OKX remains around $75,000. The difference between exchanges reflects their respective options positions, contract concentrations, and strike distributions. In other words, there is no single universal max pain price governing the entire bitcoin market.
There is an important catch, however. Max pain measures the settlement price at which aggregate option-holder payouts would be minimized, not where bitcoin is destined to trade. Market makers’ hedging activity, shifting positions, and spot-market demand can all interfere with any apparent gravitational pull toward those levels. Treating max pain as a guaranteed bitcoin price target would be playing with fire, particularly when billions of dollars in exposure can change hands before expiration.
Futures Exposure Remains Substantial Despite Cooling Activity
Meanwhile, bitcoin futures open interest stands at $51.7 billion, representing approximately 624,450 BTC across tracked exchanges. That exposure declined 1.59% over the preceding 24 hours, suggesting some leverage has been cleared even as options traders maintain substantial outstanding positions. The four-hour reading slipped 0.13%, while the one-hour figure remained essentially unchanged with a marginal 0.01% increase.
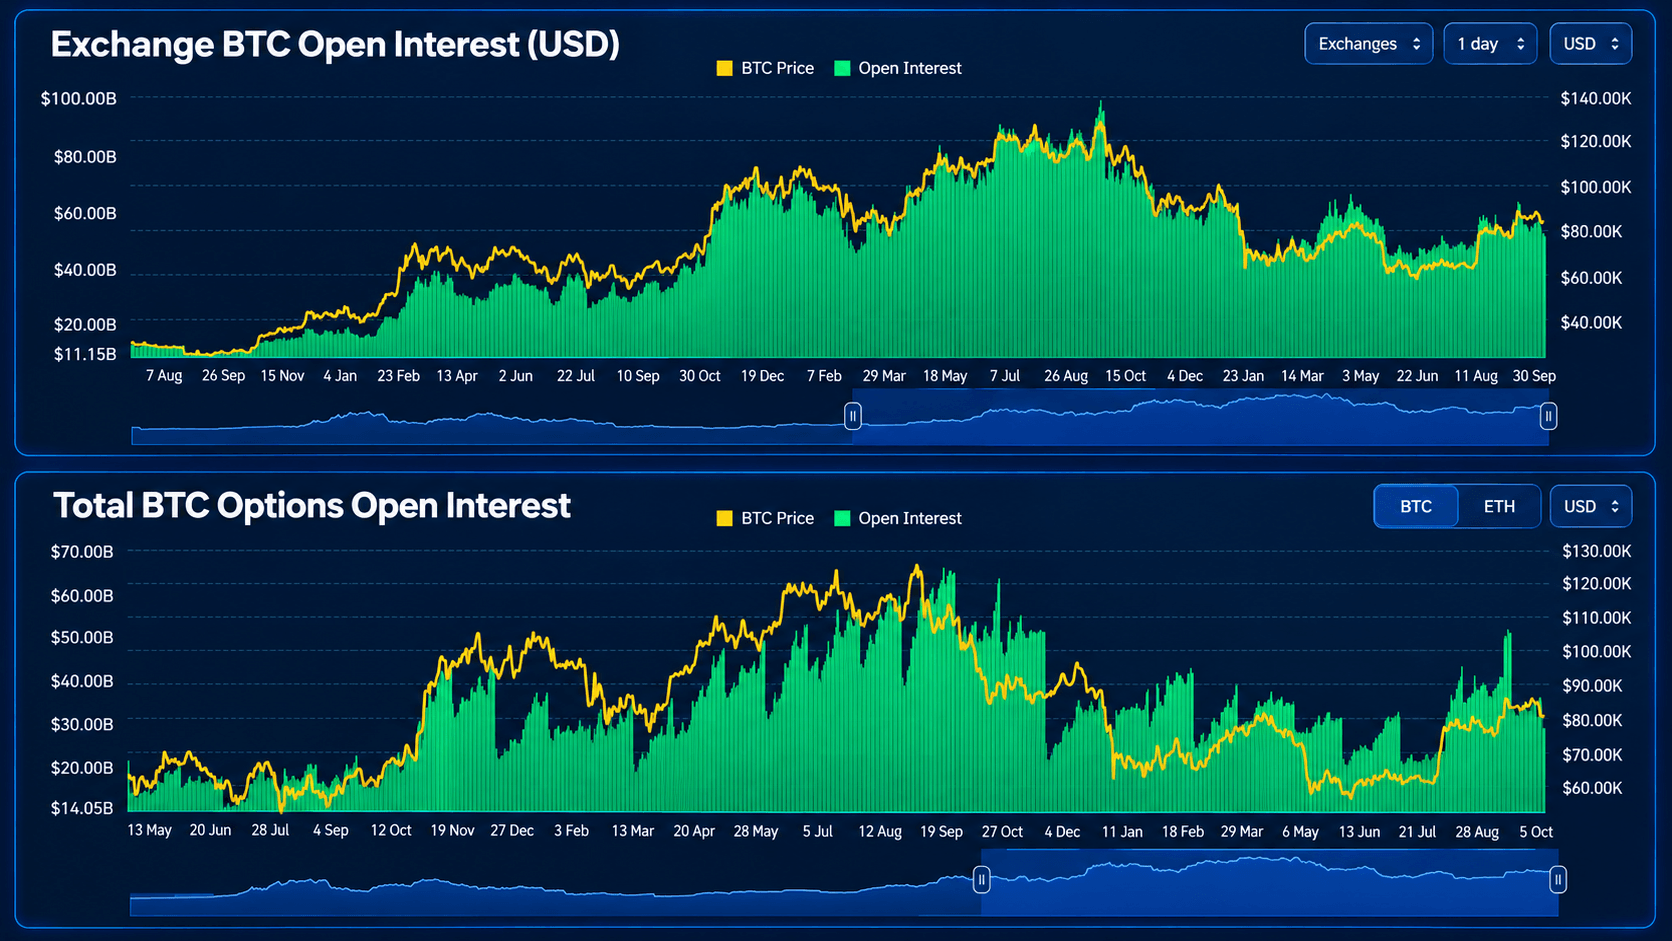
Binance leads the futures venues today with $10.78 billion in open interest, followed by CME at $8.88 billion, Bybit at $5.38 billion and Gate at $4.34 billion. CME’s exposure slipped 0.46% over the previous day, while Binance registered a modest 0.30% increase. Bybit, meanwhile, added 0.95%, indicating that leverage adjustments were far from uniform across the major trading platforms.
The broader options market has also expanded considerably from earlier periods. Coinglass historical data shows total bitcoin options open interest recently trading around $35 billion to $40 billion, following a sharp spike above $50 billion in late September. Although exposure has retreated from that local peak, the market continues to carry substantial derivatives commitments as October’s major expiration approaches.
CME Positioning Adds Another Wrinkle
Institutional positioning introduces another interesting dimension. CME options data from market analytics site Cryptoquant shows calls accounting for most of the displayed open interest by position, while the expiration breakdown reveals considerable exposure concentrated in contracts expiring within one to two months. The figures suggest that the coming weeks will be particularly important for institutional derivatives participants managing directional exposure and portfolio protection.
CME’s market data also show that outstanding options exposure has moderated from late September’s elevated readings, even as bitcoin recovered from its recent retreat toward $82,000. That combination leaves traders navigating a market where substantial bullish call exposure coexists with declining futures leverage and lower theoretical options settlement levels.
The contradiction is difficult to miss. Bitcoin sits above $82,000, traders have amassed billions in exposure at $90,000 to $100,000 strikes, and several major expiration dates carry substantially lower max pain estimates. The bulls have placed their wagers, but the options market isn’t handing them the keys just yet.
Hero/Feature image chart data: Coinglass.com